When thinking about Iran’s strategic decision-making process it may be helpful to use a framework borrowed from options markets. We use the construct as an analytical device because it offers a useful way of thinking about how the value and durability of Tehran’s leverage change with both the oil price and the political calendar. We recognize the framework abstracts from the profound human consequences of the conflict.
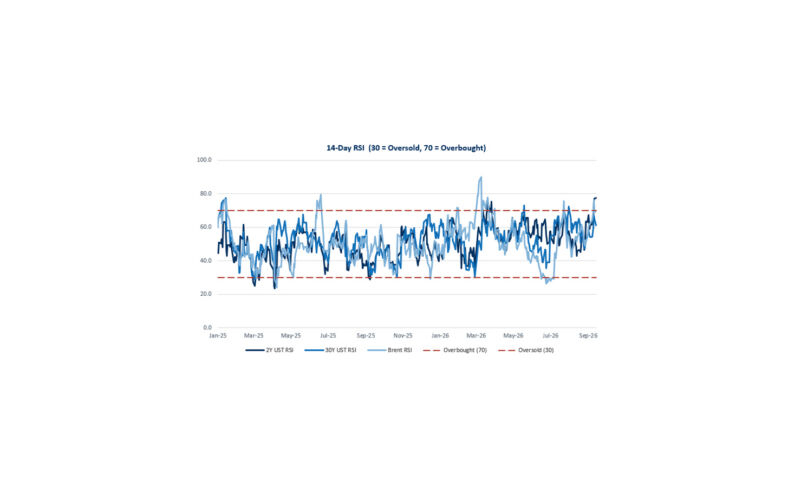
One could argue that Iran’s strategic decision calculus resembles that of being long a high-strike oil call with an expiry around the US midterms. The regime’s leverage has risen sharply as the conflict has persisted and oil has moved higher, particularly with polling suggesting that gasoline prices are politically consequential for the White House. This implies that the value of Tehran’s leverage may be greater ahead of the midterms than it will be once they have passed. With oil still trading close to local highs but beginning to show signs of upside exhaustion, and only a few weeks remaining until the midterms, one could argue that Tehran is approaching peak gamma. When close to the option strike and close to expiry, relatively small moves in the underlying produce very large changes in delta, leaving Iran with a highly convex position at precisely the point at which accelerating theta decay shortens the window in which disruption to Hormuz can be converted into maximum political pressure.
The same framework also highlights the increasingly unforgiving economics of carrying that optionality into expiry. When the underlying asset is trading close to the strike price and with little time to expiry, the gamma on the option is elevated but so too is the rate of time decay. In market terms, an option holder presented with the opportunity to crystallise a substantial portion of the position’s convexity, rather than retain exposure to a binary terminal payoff, may choose to monetise the option ahead of expiry. If Tehran is indeed approaching peak gamma, the rational conclusion may be that reopening Hormuz in exchange for an end to the war could allow it to convert a temporary and highly convex source of leverage into a more durable political outcome.
Oil is Showing Signs of Upside Exhaustion
Brent Front Future Price, Fibonacci Retracement Levels and 14d Relative Strength Index
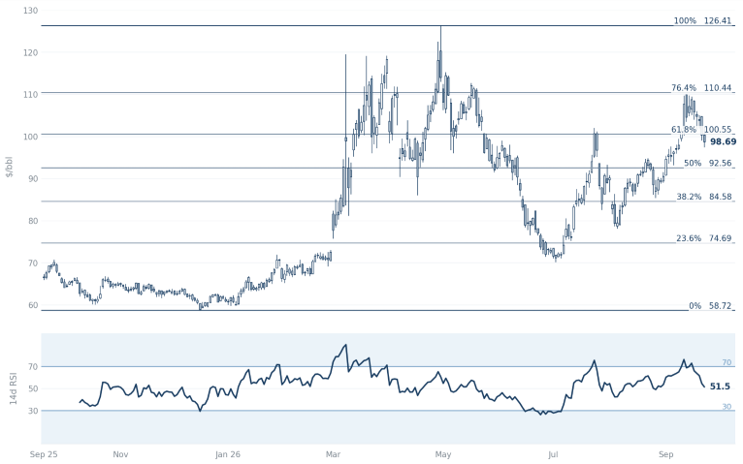
Source: Bloomberg, Citadel Securities, data as of Sep 2026. Figures are for illustrative purposes only. Past performance does not guarantee future returns.
Copyright © Citadel Enterprise Americas LLC or one of its affiliates. All rights reserved.
Legal Entities Disseminating this Material: This material is disseminated in the United Kingdom by Citadel Securities (Europe) Limited (“CDGE”) authorized and regulated by the Financial Conduct Authority (“FCA”) (Registered company number: 05462867); in the European Union by Citadel Securities GCS (Ireland) Limited (“CSGI”) and its Paris Branch authorized and regulated by the Central Bank of Ireland (“CBI”) (Registration Number: C173437); in Hong Kong by Citadel Securities (Hong Kong) Limited (“CDHK”) licensed by the Securities and Futures Commission of Hong Kong (“SFC”), in Japan by Citadel Securities Japan Co., Ltd (“CSJC”) registered as a Type 1 financial instruments business operator with the Japan Financial Services Agency (“JFSA”); and in the United States of America by Citadel Securities LLC (“CDRG”) registered with the Securities Exchange Commission (“SEC”), Financial Industry Regulatory Authority (“FINRA”), and Securities Investor Protection Corporation (“SIPC”), Citadel Securities Institutional LLC (“CSIN”) registered with the SEC, FINRA, and SIPC, or Citadel Securities Swap Dealer LLC (“CSSD”) registered with the SEC, Commodities Futures Trading Commission (“CFTC”), and National Futures Association (“NFA”). Unless governing law permits otherwise, you must contact a Citadel Securities entity in your home jurisdiction if you want to use our services in effecting a transaction in any financial instruments or securities, including derivatives.
FOR INSTITUTIONAL USE ONLY; FOR PROFESSIONAL CLIENTS AND ELIGIBLE COUNTERPARTIES ONLY. This material is not intended as and does not constitute investment research. Contents of this material will be strictly limited to non-specific, generic information (i.e. macro events/topics) and are not subject to the Markets in Financial Instruments directive (MiFID II) or FINRA research rules. This material does not constitute an offer, solicitation, invitation, or inducement to purchase, acquire, subscribe to, provide, or sell any financial instrument or otherwise engage in investment activity. Please see additional important disclosures, including disclosures that may be relevant to your country of residence or business at www.citadelsecurities.com/GlobalSalesTrading.